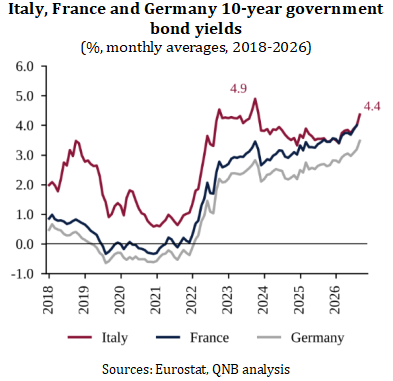
For much of the past fifteen years, Italy was regarded as one of the weaker countries in the Euro area. High public debt, chronically low growth, fragile banks and frequent changes of government made Italian government bonds (BTPs) a recurring source of market stress, from the sovereign debt crisis of 2011-12 to the budget standoff with Brussels in 2018. As recently as September 2022, amid the energy crisis and a change of government, the spread between Italian and German 10-year yields stood at 251 basis points (b.p.), a level that reflected persistent investor doubts over debt sustainability. Since then, Italy has staged a quiet but remarkable turnaround. By January 2026, the spread had compressed to 59 b.p., the tightest since 2008. More recently, Italy’s 10-year government bond yield has fallen below its French equivalent, an inversion first recorded in late 2025 and which has become more pronounced in recent weeks.
Rating agencies have followed the markets. In September 2025, Fitch upgraded Italy to BBB+, its first upgrade of the country since 2021. In November, Moody’s raised Italy to Baa2, its first upgrade in 23 years, citing political stability, prudent fiscal policy and stronger banks. In January this year, S&P moved its outlook to positive, expecting the deficit to fall below 3% of GDP in 2026. However, recent weeks have brought renewed volatility. The energy shock from the US-Iran conflict, two rate hikes by the European Central Bank (ECB) and stress in US Treasuries pushed the spread back above 100 b.p. in early October. However, this has been a broad repricing of sovereign risk across advanced economies rather than an Italy-specific event. Today, Italian bonds still trade at lower yields than French bonds.
In our view, Italy’s re-rating rests on solid ground rather than on favourable global liquidity conditions alone. The recent widening of spreads does not signal a reversal of the improvement in Italian fundamentals. In this article, we discuss three factors behind Italy’s comeback: a credible fiscal consolidation, an unusual period of political stability, and a much stronger private-sector and external balance sheet.
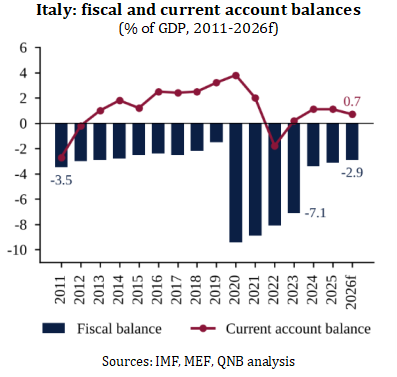
First, Italy has delivered a credible fiscal consolidation, narrowing its budget deficit faster than many expected. The general government deficit fell from 7.1% of GDP in 2023 to 3.4% in 2024 and 3.1% in 2025. For 2026, the government projects a deficit of 2.9% of GDP, within the EU’s 3% ceiling for the first time since 2019. Importantly, the adjustment has been underpinned by consistent fiscal consolidation: Italy has run a primary surplus, i.e., a budget balance excluding interest payments, since 2024. This contrasts with the primary deficit of around 1.5% of GDP for the Euro area as a whole. A primary surplus is critical for a highly indebted country, as it allows the debt ratio to stabilise even when interest costs rise. With public debt expected to peak at around 138% of GDP in 2027, this consistency has been key to restoring investor confidence. Italy: fiscal and current account balances
Second, Italy is enjoying an unusual period of political stability, which has reduced a risk premium that long weighed on its bonds. Since 1946, Italy has had close to 70 governments, with an average lifespan of little more than a year. Frequent changes of coalition and policy direction regularly unsettled investors. By contrast, the current government, in office since October 2022, is now among the longest-serving in the history of the Republic, with the same economy minister throughout. This continuity has allowed a consistent fiscal line to be maintained across successive budgets, a factor explicitly highlighted by Moody’s and Fitch in their upgrades. Political stability has also supported steady implementation of the EU-funded National Recovery and Resilience Plan (NRRP), of which Italy is the largest beneficiary, sustaining public investment and growth.
This helps explain why investors now demand a lower yield on Italian debt.
Third, Italy’s private-sector and external balance sheets are much stronger than during past episodes of stress, reducing the country’s vulnerability to shifts in investor sentiment. In 2011, at the height of the sovereign debt crisis, Italy ran a current account deficit of close to 3% of GDP and relied on foreign capital to finance it. Today, the picture has reversed. The current account recorded a surplus of 1.2% of GDP in 2025. Italy has become a net creditor to the rest of the world, with a positive net international investment position of over 15% of GDP. The banking sector has also undergone a deep transformation. Gross non-performing loans, which exceeded 15% of total loans in the mid-2010s, have fallen to around 2%, while the largest lenders posted record profits in 2025 and hold comfortable capital buffers. Stronger banks weaken the “doom loop” between sovereign and bank risk that amplified previous crises, giving Italy a resilience it lacked in the past.
All in all, Italy’s structural re-rating reflects a credible fiscal consolidation, political stability and much stronger private-sector and external balance sheets. While the global repricing of sovereign risk has pushed spreads wider in recent weeks, we expect Italian spreads to remain below their historical stress levels. The key test lies ahead. With the deficit projected to rise back to 3.4% of GDP in 2027 to fund defence and energy needs, and general elections due later that year, preserving fiscal discipline will be essential to consolidate Italy’s hard-won credibility.
DISCLAIMER: The information in this publication (“Information”) has been prepared by Qatar National Bank (Q.P.S.C.) (“QNB”) which term includes its branches and affiliated companies. The Information is believed to be, and has been obtained from, sources deemed to be reliable; however, QNB makes no guarantee, representation or warranty of any kind, express or implied, as to the Information’s accuracy, completeness or reliability and shall not be held responsible in any way (including in respect of negligence) for any errors in, or omissions from, the Information. QNB expressly disclaims all warranties or merchantability or fitness for a particular purpose with respect to the Information. Any hyperlinks to third party websites are provided for reader convenience only and QNB does not endorse the content of, is not responsible for, nor does it offer the reader any reliance with respect to the accuracy or security controls of these websites. QNB is not acting as a financial adviser, consultant or fiduciary with respect to the Information and is not providing investment, legal, tax or accounting advice. The Information presented is general in nature: it is not advice, an offer, promotion, solicitation or recommendation in respect of any information or products presented in this publication. This publication is provided solely on the basis that the recipient will make an independent evaluation of the Information at the recipient’s sole risk and responsibility. It may not be relied upon to make any investment decision. QNB recommends that the recipient obtains investment, legal, tax or accounting advise from independent professional advisors before making any investment decision. Any opinions expressed in this publication are the opinions of the author as at the date of publication. They do not necessarily reflect the opinions of QNB who reserves the right to amend any Information at any time without notice. QNB, its directors, officers, employees, representatives or agents do not assume any liability for any loss, injury, damages or expenses that may result from or be related in any way to the reliance by any person upon the Information. The publication is distributed on a complementary basis and may not be distributed, modified, published, re-posted, reused, sold, transmitted or reproduced in whole or in part without the permission of QNB. The Information has not, to the best of QNB’s knowledge, been reviewed by Qatar Central Bank, the Qatar Financial Markets Authority, nor any governmental, quasi-governmental, regulatory or advisory authority either in or outside Qatar and no approval has been either solicited or received by QNB in respect of the Information.